I want to talk about what's happening in the energy markets right now, because energy is driving a lot of what we're seeing in inflation, interest rates, and the capital markets every single day. I'll be upfront: this is a genuinely complicated topic, and I don't think it does anyone justice to boil it down to a single headline number. The people who do that—often for political reasons—tend to leave out something important. So, bear with me. I want to walk through the fundamentals first, because once you understand how the pieces fit together, the diesel price you're paying at the pump, and the interest rate decisions coming out of the Fed, make a lot more sense.
Let’s start with the basics. Energy is a global market, and even today, roughly 80% of the world's energy still comes from carbon-based sources: oil, coal, and natural gas combined, according to the Energy Institute's Statistical Review of World Energy. The rest comes from nuclear, hydro, wind, and other renewables. And overall global energy use keeps climbing, at a meaningful pace.
You've probably heard that AI and data centers are behind a lot of the new demand. That's true, but the number gets exaggerated if you're not careful about scope. Globally, data centers still make up a small share of total electricity use, under 2%, per the International Energy Agency. But here in the U.S. specifically, data centers accounted for roughly half of all electricity demand growth in 2025, and the IEA expects that share to hold through 2030. In other words, it's not that data centers are eating up a huge chunk of the world's power yet—it's that almost all of our new domestic demand is coming from that one source, which is straining local grids even while the global energy mix barely moves.
To understand why energy moves the way it does, you have to go back further than most people think. The global energy trade is really just one piece of a century-long march toward globalized trade generally. The U.S. became the anchor of that system after World War II, when we emerged as the dominant naval power and effectively became the guarantor of freedom of the seas for every country, not just ourselves.
That role is why global shipping costs have stayed so low for so long. It's why containerized shipping works: goods move in standardized boxes that can go almost anywhere. And it's why manufacturers can shop the globe for the cheapest raw materials and labor. All of that keeps inflation lower, including energy inflation.
That role came into question after the U.S. left Vietnam in the 1970s without the outcome we wanted. Our credibility as the backbone of the global trading system was genuinely at risk. Desert Shield and Desert Storm, now 35 years ago, reasserted U.S. military reach in a way that, frankly, I don't think gets enough credit today. It paved the way for safer sea lanes ever since, which also means lower shipping insurance costs, since virtually everything that moves by sea, including oil, is insured. All of this built the assumption, mostly unconscious for the average consumer, that oil and other goods can move freely and cheaply almost anywhere in the world.
This is where it gets interesting. Oil in the U.S. isn't owned or produced by the federal government—it's produced by for-profit companies like ExxonMobil and Chevron, plus foreign-owned operators like BP and Total. I like to compare it to U.S. auto manufacturing: the government doesn't make cars, but Ford, GM, Toyota, and Hyundai all manufacture here. Same idea with oil. When people talk about “U.S. oil production,” they mean production happening within U.S. borders by private companies, not government output.
With that framing, here's the history. The U.S. was a net energy importer for 67 straight years, from 1952 until 2019, when for the first time in that span, we became a net energy exporter, according to the EIA. U.S. crude production has climbed for four decades, across administrations of both parties, and hit a record of roughly 13.5 million barrels a day in 2025.
So by the broadest measure, yes, we're “energy independent.” But—say it with me—it's more complicated than that.
Here's the twist: U.S. refineries process roughly 17 million barrels of crude a day—more than the roughly 13.5 million barrels we produce domestically. We’re a net importer of crude even though we're a net exporter of energy overall; those two facts aren't actually in conflict once you look at the mechanics. Total U.S. refining capacity tops out around 18.4 million barrels a day at full run rates, per EIA data.
The gap gets filled mostly by Canada, which supplies more than 60% of all U.S. crude imports. Total crude imports run around 6 to 6.5 million barrels a day, and exports run around 4 million, for a net import figure in the 2-to-3-million-barrel range.
Why import at all if we produce so much? Because of the type of oil. Most U.S. shale production is light, sweet crude, which is shorter hydrocarbon chains. Most U.S. refineries are built to run a medium-to-heavy blend, so we import heavier crude, largely from Canada, and blend it with our own lighter crude, while exporting a lot of our excess light crude to refineries elsewhere in the world that are built for it. Refiners then “crack” that blend into everything from propane and gasoline to diesel and jet fuel. When this system works efficiently, none of it matters to you at the pump. Right now, it matters a lot.
This is the heart of the story. As of mid-September, U.S. retail diesel prices were $6.50 / gallon (with prices fluctuating daily), per EIA data—the highest nominal price on record since EIA started tracking the series in 1994. And here's the part that surprises people: the U.S. actually produces more diesel than it uses. We refine somewhere around 5.1 to 5.25 million barrels of diesel a day and only consume about 4 million, making us a net exporter of roughly 1 to 1.25 million barrels a day.
Why are prices so high if we have a surplus? Because diesel is priced on the global market, and that market is under real strain right now. Three things are hitting at once: the conflict disrupting shipping and supply through the Middle East and the Strait of Hormuz; Russia's ban on diesel exports after drone strikes knocked out a meaningful share of its refining capacity; and China and India both limiting their own diesel exports. Meanwhile, U.S. distillate inventories are running well below their five-year seasonal average, right as we head into the higher-demand winter heating season.
You can see the strain most clearly in the crack spread: the refining margin between the cost of crude and the value of what refiners sell. The blended 3-2-1 crack spread (2 barrels of gasoline plus 1 barrel of diesel, from every 3 barrels of crude) sat around $73 a barrel in late September, close to the record set during the 2022 spike. The diesel-specific margin has gone even further, briefly topping $106 to $110 a barrel, an all-time high. For context, that margin has historically averaged closer to $19 a barrel going back to 2006, so this is a genuinely unusual environment, not a routine seasonal move.
My take: This is enormously profitable for U.S. refiners right now, and I don't say that as a criticism—that's what companies in a capitalist system do when margins widen. But it's also a real cost being passed straight through to consumers and businesses, because nearly every good you buy touches a diesel-powered truck, train, or ship at some point on its way to you.
“The U.S. produces more diesel than it uses. The problem isn't a shortage — it's that diesel is priced on a global market, and that market is under real strain.”
This idea gets floated whenever diesel prices spike, and it's worth taking seriously. In the short run, restricting U.S. diesel exports would almost certainly lower domestic prices from $6.50 down toward the $5 range, though it's hard to say exactly how much. But it would come with real costs. It would tighten an already-thin global diesel market further, which would raise prices for our allies, many of whom, especially in Europe, are already facing dwindling distillate stockpiles heading into winter.
It probably wouldn't last, either. U.S. refiners are for-profit companies, not a nationalized industry, and if they can't export their surplus, they'll likely cut production to match a smaller addressable market rather than run at a loss domestically. That would erase a lot of the relief fairly quickly. Short of the U.S. deciding to nationalize how it manages energy markets—which isn't remotely on the table—that outcome looks close to inevitable if export limits were imposed. It's also worth remembering the oil industry carries real lobbying weight in Washington and has historically benefited from favorable tax treatment, so a move like this would face real political friction, too.
This is where energy stops being a niche topic and starts affecting your portfolio directly. High diesel prices work their way into the price of almost everything, because almost everything moves by truck, rail, or ship at some point. That's the “diesel-flation” story, and it's a big part of why the Fed raised rates a quarter point earlier this month—its first hike since 2023—in a unanimous 12-0 vote.
Markets are currently pricing in roughly three to four more quarter-point hikes between now and the middle of 2027, based on fed funds futures, though that number moves daily as new data comes in. The 10-year Treasury yield is sitting close to 5%, its highest level in close to two decades, and 30-year fixed mortgage rates have pushed north of 7%.
The bigger question behind all of this is how the Fed threads the needle on a supply-driven inflation problem, which is much harder to manage with rate policy than an ordinary demand-driven one. We touched on that dynamic in our recent post on Kevin Warsh and the Fed's balance sheet: rate policy alone can't fix a shipping lane or a damaged refinery. Ultimately, how this resolves depends more on what happens with the conflicts in the Middle East and with Russia and Ukraine than on anything the Fed decides in a given month. Nobody, including us, has a confident prediction on that timeline. But the Treasury market is making its own prediction right now, and it's pricing in more inflation and higher rates for a while yet.
This backdrop looks a lot like 2022, when the Fed was late to respond to inflation and long-duration bonds got hit hard: the Bloomberg U.S. Aggregate Bond Index fell more than 13% that year, its worst performance ever. We're running a similar playbook again. The majority of our clients' fixed income exposure sits in short-term or floating-rate structures, including our short-term tactical strategy, built specifically to have minimal sensitivity to rising rates or widening credit spreads. That positioning means most client portfolios have been largely insulated from this year's move in rates, even as broad bond benchmarks have had a difficult year.
On the equity side, our approach hasn't changed. For clients who are adding to their portfolios, a pullback would be a welcome chance to add equity exposure at cheaper prices. For clients who aren't adding, we've been taking profits along the way as markets have rallied, consistent with each client's long-term plan and risk budget. None of this is a market call—it's discipline we'd apply in any environment.
I don't have a clean prediction here, and I'd be skeptical of anyone who tells you they do. There's real risk around inflation, real risk around energy prices, and real risk tied to military outcomes nobody can forecast with confidence.
“What I can tell you is that we're watching all of this closely, and we've already positioned client portfolios for a world where rates stay higher for longer rather than betting on a quick reversal.”
If you'd like to talk through how this environment affects your specific plan, reach out to us to connect with a BIP Personal Wealth advisor.
Diesel prices just hit an all-time high in the U.S.—not because we're short on oil, but because refining margins have blown out to levels never seen before. Three things are colliding at once: the conflict disrupting shipping through the Middle East, a Russian diesel export ban after drone strikes knocked out a chunk of its refining capacity, and thin seasonal inventories heading into winter. The U.S. actually produces more diesel than it uses, but diesel is priced on a global market, so that surplus doesn't protect us at the pump. This is a supply shock, not a demand story, and supply shocks are the hardest kind for the Fed to manage with interest rate policy. That's part of why the Fed just hiked rates for the first time since 2023, and futures markets are pricing in three to four more quarter-point hikes by the middle of 2027. At BIP, we've kept our fixed income positioning short-duration and floating-rate—the same playbook we’ve run since 2022—so client portfolios are largely insulated from this move in rates.
This post is intended for informational purposes only. Specific investments may not be suitable for all investors and no offer or recommendation of any investment or investing strategy is intended or implied by your choosing to read this post. The opinions in this commentary are as of the date of publication and are subject to change. Information has been obtained from third-party sources we consider reliable, but we do not guarantee the facts cited are accurate or complete.
BIP Wealth, LLC (“BIP Wealth”) offers investment advisory services and is registered with the U.S. Securities and Exchange Commission (“SEC”). Registration with the SEC as a registered investment adviser does not imply a certain level of skill or training. For more information about BIP Wealth, please refer to our Form ADV, available at adviserinfo.sec.gov or upon request.
Statements regarding BIP Wealth's past or current portfolio positioning are historical in nature and are not indicative of future results or actions. References to the Bloomberg U.S. Aggregate Bond Index are for illustrative purposes only; indices are unmanaged and not available for direct investment. Past performance is not a guarantee of future results. Short-duration and floating-rate fixed income investments may reduce interest-rate sensitivity, but they carry other risks and may underperform alternative strategies in different market environments.
The Federal Reserve raised its benchmark interest rate by a quarter point yesterday, its first increase since 2023. Here’s my take on what happened and what I’m going to continue to watch.
In a unanimous vote, 12-0, the Federal Open Market Committee (FOMC) raised the federal funds rate by 25 basis points, moving the target range to 3.75%-4.00%. It's the first hike since the Fed wrapped up its post-pandemic tightening campaign in 2023, and officials' own projections point to at least one more increase before year-end.
I think the committee got this one right.
This is the part I want clients to understand clearly: Energy markets are under real strain. Oil, and diesel in particular, have surged as conflict in the Middle East disrupts supply. Diesel powers the trucks and trains that move nearly everything we buy, so those costs work their way into the price of just about everything else.
This may remind you of the inflation surge from a few years ago, and it should. Both were caused by a supply shock, not an overheating economy. During COVID, supply chains were damaged when Russia invaded Ukraine and when China imposed a zero-tolerance policy that kept workers sidelined. Yesterday’s shock is different in cause but similar in effect: diesel and other distillates are simply less available, and that scarcity is pushing prices up.
Here's why that history matters: last time, the Fed held rates near zero for too long rather than raise them against a shock it couldn't control. Inflation eventually hit 9%, and by the time the Fed responded, it was playing catch-up. I don't think that mistake is repeating itself.
"Yesterday's vote suggests this Fed learned that lesson—it's moving early rather than waiting to see if a supply shock turns into something worse."
This hike didn't happen in a vacuum. The White House has pushed publicly for lower rates, with President Trump recently threatening to halt trade with any country the U.S. runs a deficit with unless the Fed cuts. Fed Chair Kevin Warsh moved ahead with a hike anyway.
My take: Kevin Warsh stuck to his guns and did what almost everybody else was concluding was the right thing to do. There are still some voices advocating for lower interest rates, but most people worried about long-term inflation felt like raising rates now was the best way to contain it.
Markets have taken it in stride so far, and are even rallying, but I’m not ready to call this settled yet. If the White House escalates its response, or if Warsh signals another hike coming later this year, this could get more complicated before it gets simpler.
There’s two areas worth watching beyond stocks: a stronger dollar, which tends to follow higher rates, and pressure on crypto, which has been up and down since the announcement.
Sometimes the market takes a day or two to decide what it's going to do. In other words: don't read too much into any single day's reaction, including today's.
The Fed raised rates a quarter point today in a unanimous decision, 12-0, its first hike since 2023, driven by energy-related inflation rather than an overheating economy. It's a sign the current Fed may be more willing to act early than its predecessor was. But with political pressure mounting and at least one more hike potentially on the table this year, BIP will be watching closely for what comes next. If your portfolio needs a closer look given the environment, reach out to us to connect with a BIP Personal Wealth advisor.
This post is intended for informational purposes only. Specific investments may not be suitable for all investors and no offer or recommendation of any investment or investing strategy is intended or implied by your choosing to read this post. The opinions in this commentary are as of a specific date and are subject to change. Information has been obtained from third-party sources we consider reliable, but we do not guarantee the facts cited are accurate or complete.
BIP Wealth, LLC (“BIP Wealth”) offers investment advisory services and is registered with the U.S. Securities and Exchange Commission (“SEC”). Registration with the SEC as a registered investment adviser does not imply a certain level of skill or training. For more information about BIP Wealth, please refer to our Form ADV, available at adviserinfo.sec.gov or upon request.
If you only looked at the headline numbers, the second quarter of 2026 looked almost too good to be true. In our Q3 2026 Quarterly Market Report, BIP Wealth's Chief Investment Officer, Eric Cramer, CFP®, CFA®, walked through what happened in the markets during Q2, why the rotation between growth and value keeps reversing itself, and why "sticking with the math" is the theme of the quarter.
Here's a summary of Eric's main talking points. You can also watch the full recording of the presentation below.
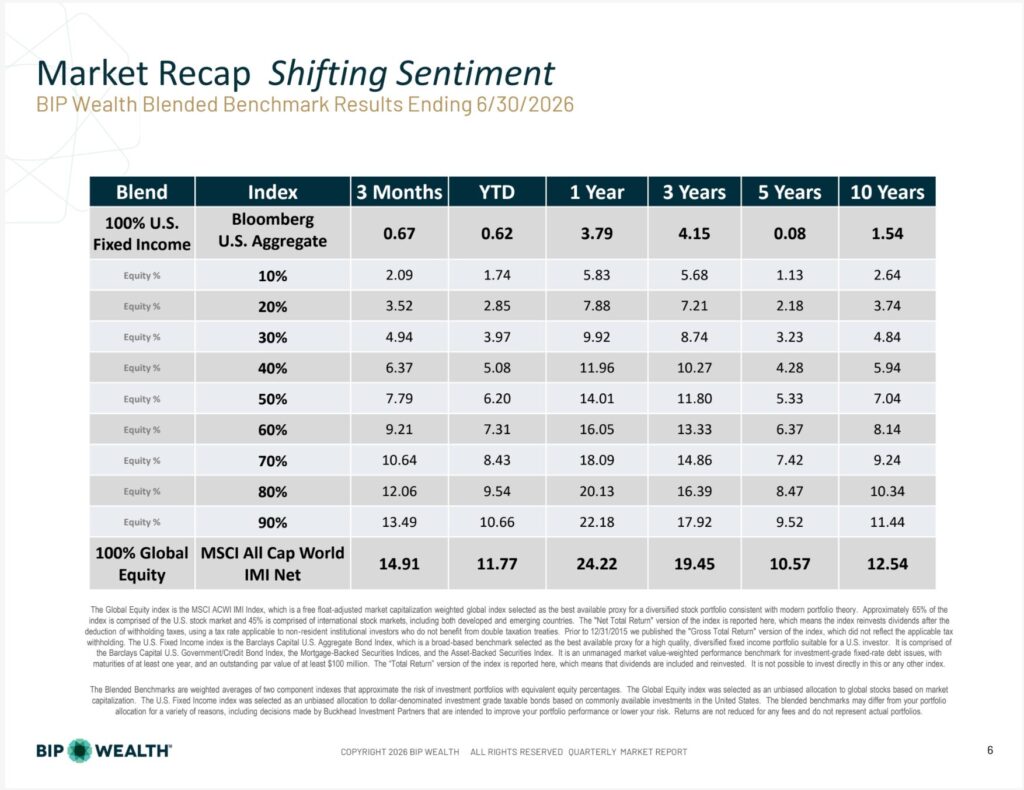
Source: MSCI, Bloomberg. For illustrative purposes only. Past performance is not a guarantee of future results. Returns are not reduced for any fees and do not represent actual portfolios.
The MSCI All Cap World IMI Net Index, our proxy for global equities, returned 14.91% for the quarter and 24.22% over the trailing year. As Eric put it, that's nearly two years' worth of long-run returns compressed into three months.
Emerging markets led the pack, returning 24.05% for the quarter alone, ahead of U.S. stocks (15.43%), international developed markets (10.22%), and global real estate (10.76%). Fixed income, by contrast, barely moved: the Bloomberg U.S. Aggregate Bond Index returned just 0.67% for the quarter and 0.62% year-to-date.
That gap is a reminder of something Eric comes back to often: benchmark returns over long stretches never show the bad headlines along the way. The 1-, 3-, 5-, and 10-year numbers all look smooth and upward-sloping. It's only when you zoom into any single quarter that you see how much the ride actually moves around.
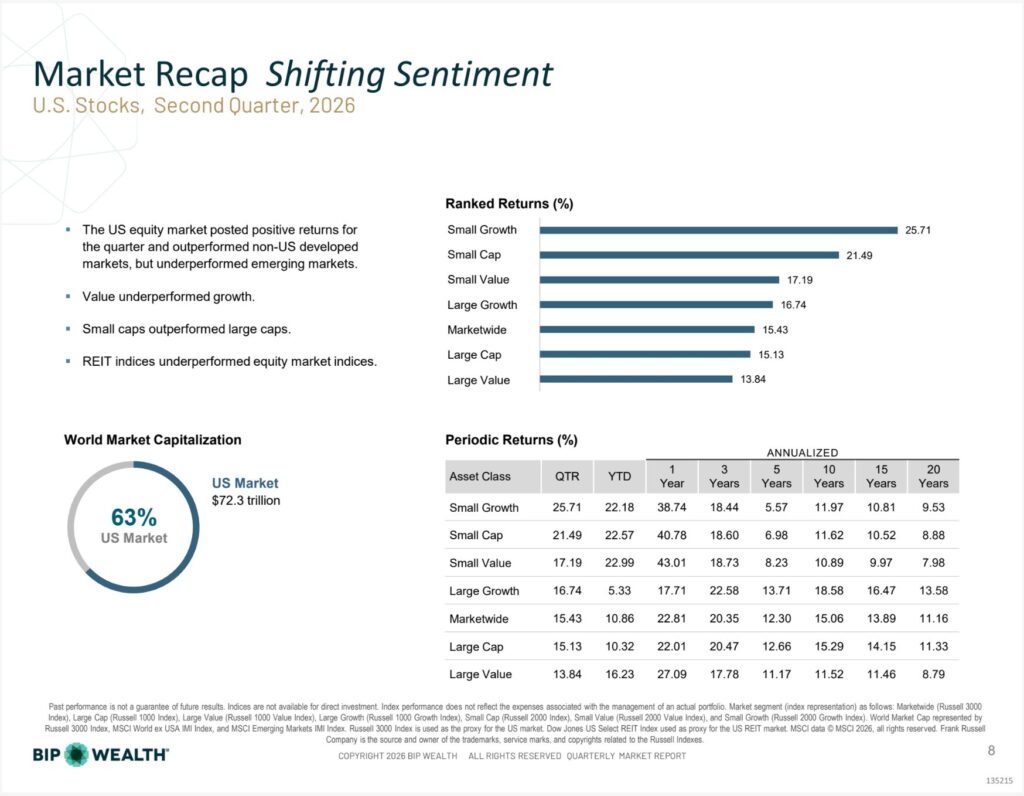
Source: Russell 3000, Russell 1000, Russell 2000 indices. For illustrative purposes only. Past performance is not a guarantee of future results. Indices are not available for direct investment.
Within U.S. stocks, small caps and growth led the quarter. Small Growth returned 25.71%, Small Cap 21.49%, and Marketwide 15.43%. That's the opposite of what happened just one quarter earlier, when value led and growth lagged, and by Eric's account, the trend has already flipped again early in early Q3. Since the beginning of 2025, we've had these alternating quarters. Growth does better and it's the tech stock rally, and then tech stocks get punished.
"That's why BIP Wealth's data goes back decades rather than quarters. Zoom out to 10 or 20 years and small-cap value's edge over growth narrows or disappears depending on the window you choose—a good illustration of why chasing whichever style just won isn't a strategy."
International developed markets told a similar story: Growth led at 12.56% for the quarter versus Value's 8.15%. In emerging markets, growth also outpaced value for the quarter, though value has meaningfully outperformed growth over the trailing 5-year period. Pick your time frame, and the same data can tell a different story.
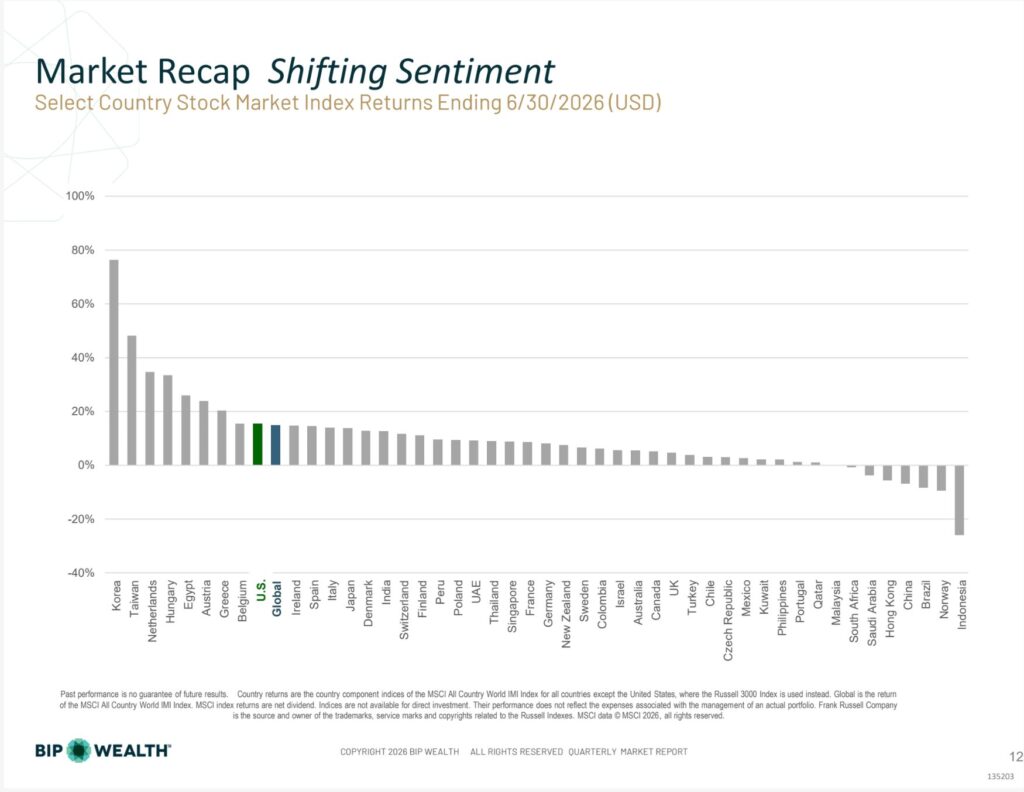
Source: MSCI All Country World IMI Index; Russell 3000 Index (U.S. proxy). For illustrative purposes only. Past performance is not a guarantee of future results.
Country-level dispersion was extreme. Korea led all major markets with a roughly 76% one-year return, driven substantially by semiconductor exposure, even as, in Eric's words, that same sector has recently started "getting destroyed" as AI-infrastructure valuations wobble. The U.S. and global benchmarks landed in the middle of the pack, both right around 14 to 15%, while a handful of markets, including Indonesia and Brazil, posted negative returns for the period.
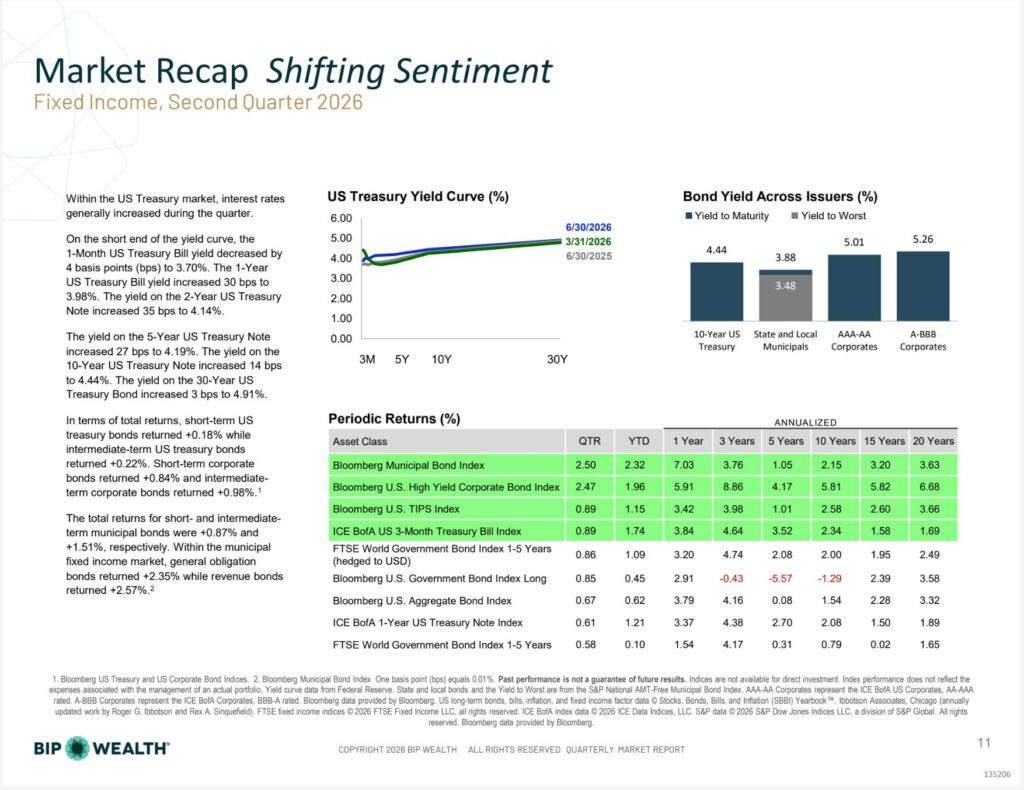
Source: Bloomberg, Federal Reserve, S&P, and ICE BofA index data. For illustrative purposes only. Past performance is not a guarantee of future results. Indices are not available for direct investment.
Yields rose across most of the Treasury curve during the quarter. The 10-Year Treasury yield climbed to 4.44%, and the 30-Year moved to 4.91%. Because bond prices move inversely to yields, that pressured returns on longer-duration bonds even as income kept accruing.
Eric's larger point is that the public fixed income in most portfolios, the ETFs and mutual funds clients typically see, is intentionally conservative. BIP Wealth tends to keep interest-rate and credit risk modest in that public bucket, and looks instead to private markets for fixed income exposure meant to generate more meaningful return.
Source: Illustrative hypothetical indices. Past performance is not a guarantee of future results. Asset Classes are used for illustrative purposes only and do not include expenses or other costs.
This quarter's Market Outlook title came from a simple idea: predicting the future requires making assumptions, and those assumptions matter enormously, even though almost nobody ever asks to see them.
Eric walked through a few of the building blocks that go into BIP Wealth's financial planning models:
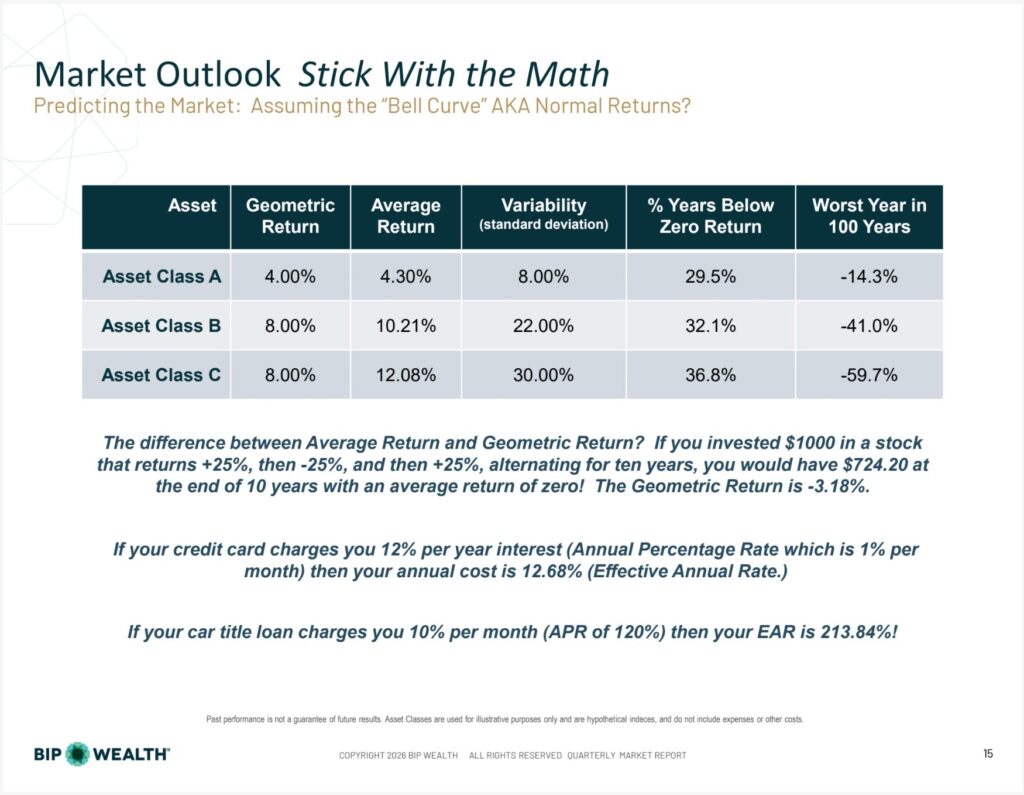
Average return isn't the same as geometric (compounded) return. If a hypothetical $1,000 investment goes up 25%, down 25%, up 25%, down 25%, and up 25% over five swings, the average return is exactly zero, but the ending balance would be $724.20, a geometric return of roughly -3.18% per year. The more volatile an investment is, the bigger that gap gets. It's the same math that explains why a credit card's 12% APR actually costs 12.68% once monthly compounding is factored in, and why a 10%-per-month car title loan, at a 120% APR, has an effective annual rate of 213.84%.
Variability cuts both ways. A safer, lower-return asset class and a higher-return, more volatile one can have a similar share of down years, but the size of the bad years is dramatically different. That's the trade-off investors make every time they choose how much risk to take.
Correlation is what makes diversification work. Two asset classes that move in perfect lockstep don't provide any real diversification benefit. The value of combining, say, U.S. and international stocks comes from the fact that they don't move exactly together, even though both are expected to be productive over time.
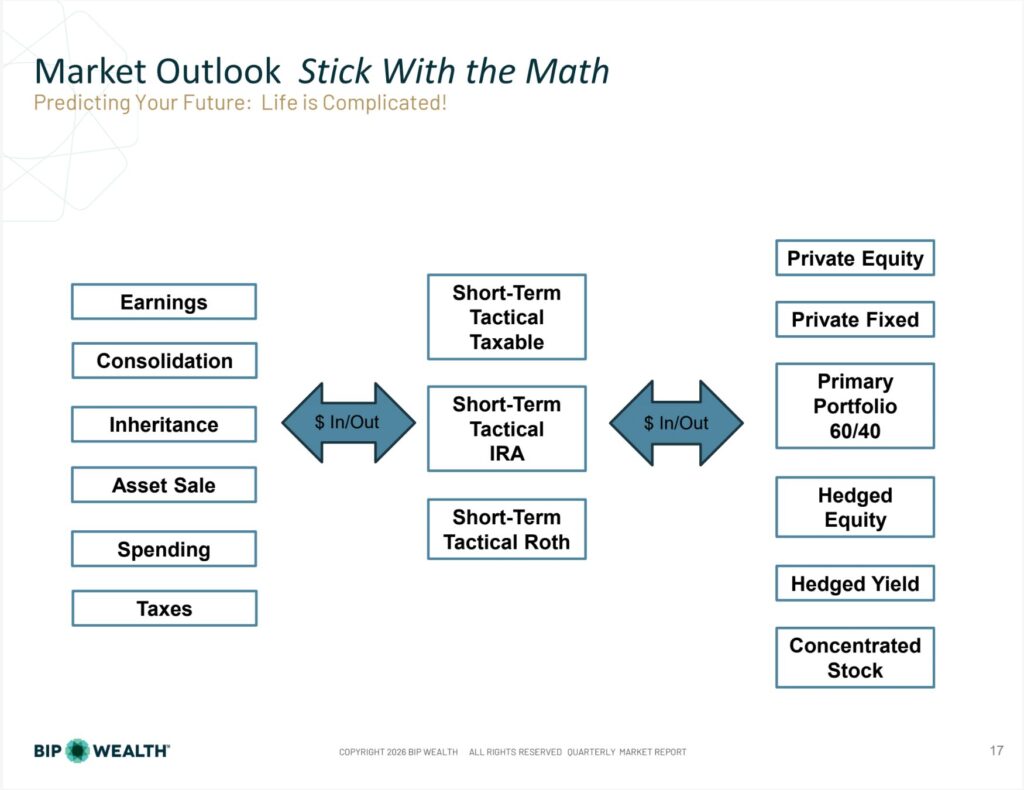
The second half of Eric's presentation shifted from markets to the other half of every financial plan: you.
"Real financial plans aren't a single lump sum growing quietly in the background. Money flows in from earnings, inheritances, and asset sales, and flows out through spending, taxes, and major purchases, often across a half-dozen different account types and strategies at once. Modeling that accurately, and adjusting it as life changes, is where much of the real planning work happens."
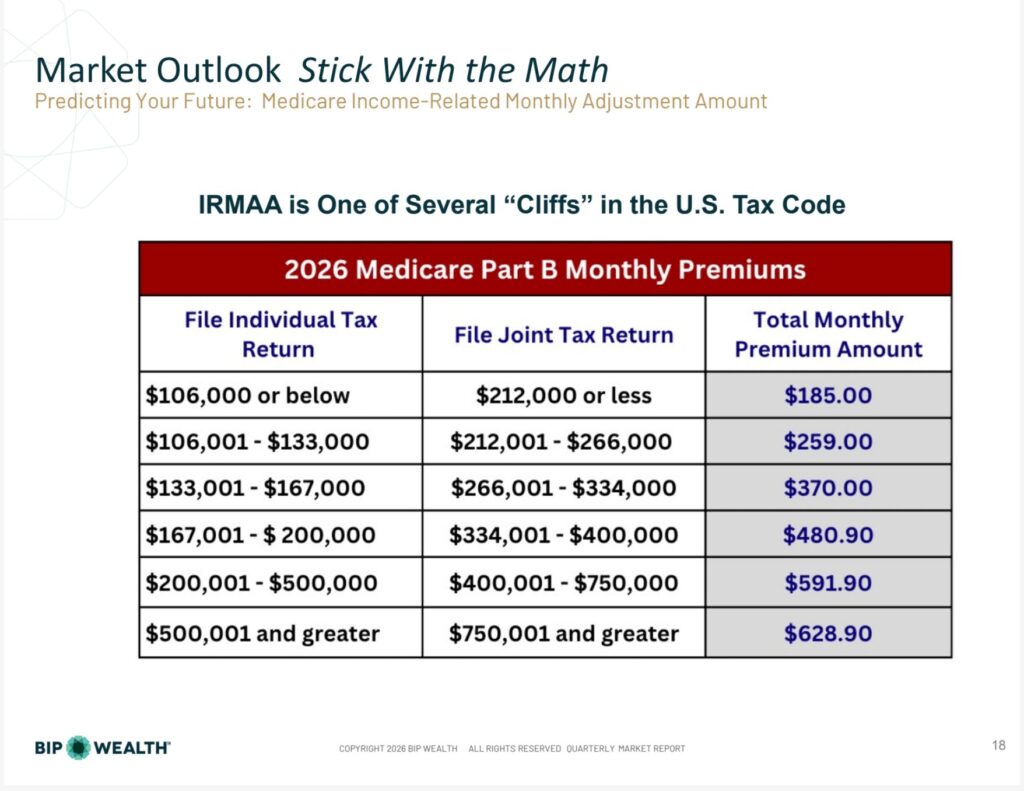
A few of the specific opportunities Eric highlighted:
IRMAA is a cliff, not a ramp. Medicare's Income-Related Monthly Adjustment Amount jumps in discrete steps based on income. Cross a threshold by even a dollar, and the monthly premium adjustment jumps with it. That makes year-end income timing decisions, like when to realize gains, genuinely worth planning around.
Source: Mandsager, Harg, Cremer et al. 2018.
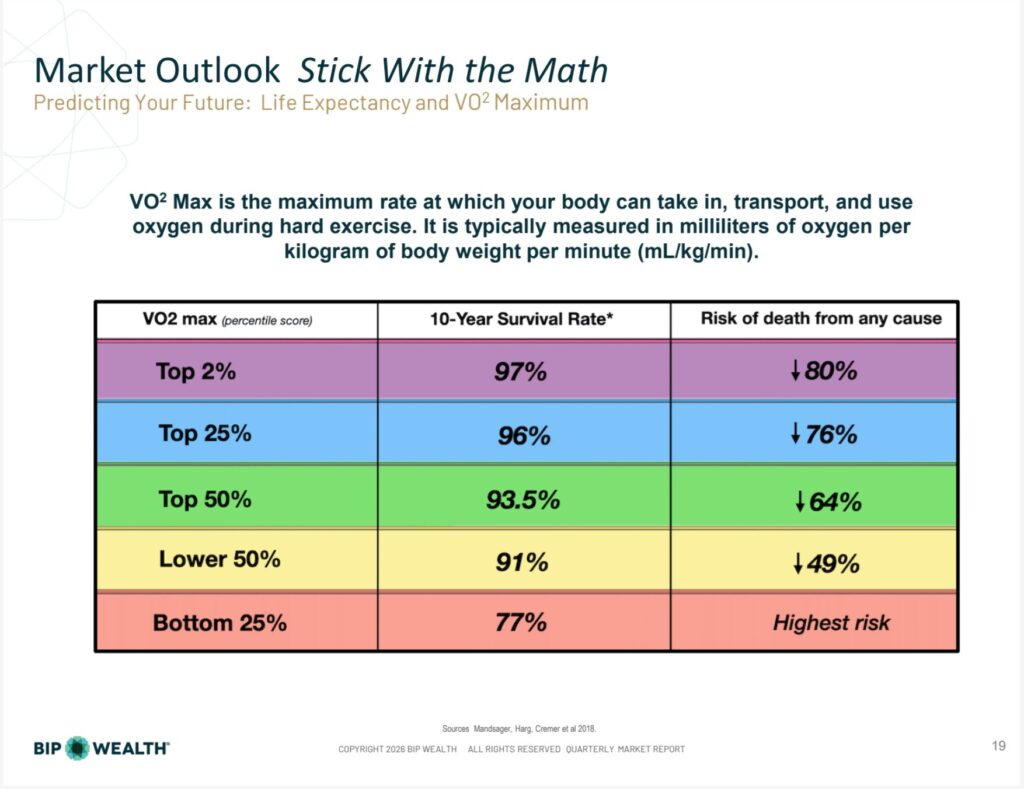
Fitness level is a meaningful predictor in a financial plan. VO2 max, a measure of how efficiently the body uses oxygen during hard exercise, is one of the strongest predictors of life expectancy available. In the study Eric cited, people in the top 2% for VO2 max had a 97% ten-year survival rate, compared with 77% for the bottom 25%, and a roughly 80% lower risk of death from any cause relative to the lowest-performing group.
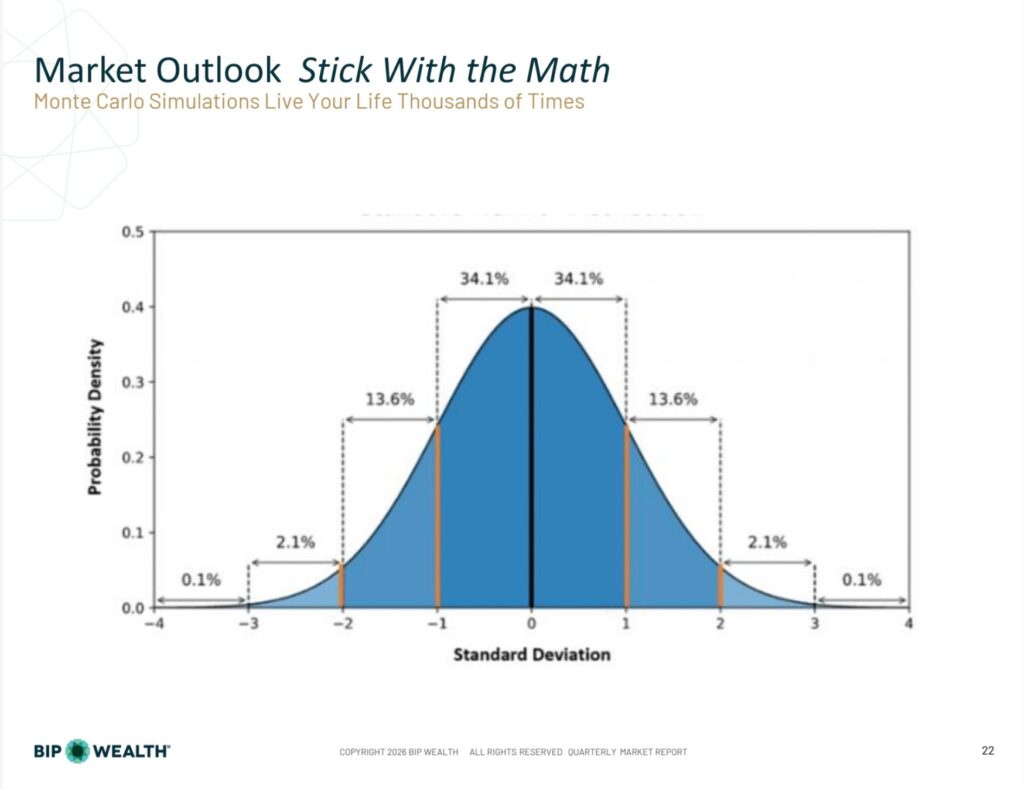
Monte Carlo simulation is how BIP Wealth turns assumptions into a probability. Rather than assuming a fixed average return, the planning software effectively lives out a client's full financial life thousands of times, varying market returns, life expectancy, spending, and other inputs each time, then counts how often the plan succeeds. Eric likens it to reliability engineering, the discipline behind testing how spacecraft and aircraft hold up under stress: a "95% chance of success" on a financial plan means it holds up in all but the least likely, worst-case outcomes. For context, Eric noted that the space shuttle program's own reliability engineering put the odds of a flight without a major incident at roughly one in 35, a reminder that even a plan built to a lower success rate than most people expect can still reflect a carefully engineered level of risk.
Eric's closing message echoed the same discipline BIP Wealth has emphasized all year. As he put it, "the markets, the stock market, are just one element of that math equation." Life expectancy, spending goals, tax rules, and personal priorities around what clients want to leave behind all shape a plan as much as expected returns do, and two clients with identical portfolios can end up with dramatically different plans once those personal variables are factored in.
"Doing the math on your specific situation is critical."
Our team's approach to evidence-based investing means continually re-examining assumptions rather than assuming the future will look exactly like the past. Our core message for investors hasn't changed: stay diversified, keep your financial plan current, and let the math, not the headlines, guide the decisions.
If you have questions about how any of this applies to your situation, reach out to connect with a BIP Personal Wealth advisor.
This blog is provided for informational purposes only. Specific investments may not be suitable for all investors and no offer or recommendation of any investment or investing strategy is intended or implied by your choosing to read this blog. Past performance is no guarantee of future results. All investments involve risks including loss of principal.
This material is not intended to be relied upon as a forecast or investment advice regarding a particular investment or the markets in general, nor is it intended to predict or depict the performance of any investment. The opinions in this commentary are as of a specific date and are subject to change. Information has been obtained from third-party sources we consider reliable, but we do not guarantee the facts cited are accurate or complete. .
BIP Wealth, LLC (“BIP Wealth”) offers investment advisory services and is registered with the U.S. Securities and Exchange Commission (“SEC”). Registration with the SEC as a registered investment adviser does not imply a certain level of skill or training. For more information about BIP Wealth, please refer to our Form ADV, available at adviserinfo.sec.gov or upon request.
If you've been following the financial headlines lately, you've probably heard the word "stagflation" more than once. It's a term that means something very specific—and something most investors haven't had to seriously contend with for four decades. In our Q2 2026 Quarterly Market Report webinar, BIP Wealth’s Chief Investment Officer, Eric Cramer, CFP®, CFA®, walked through what happened in markets during the first quarter, where he thinks inflation and economic growth are headed, and why now is exactly the right time to stay disciplined.
Here's a summary of Eric’s main talking points for this quarter. You can also watch the full recording of the webinar below.
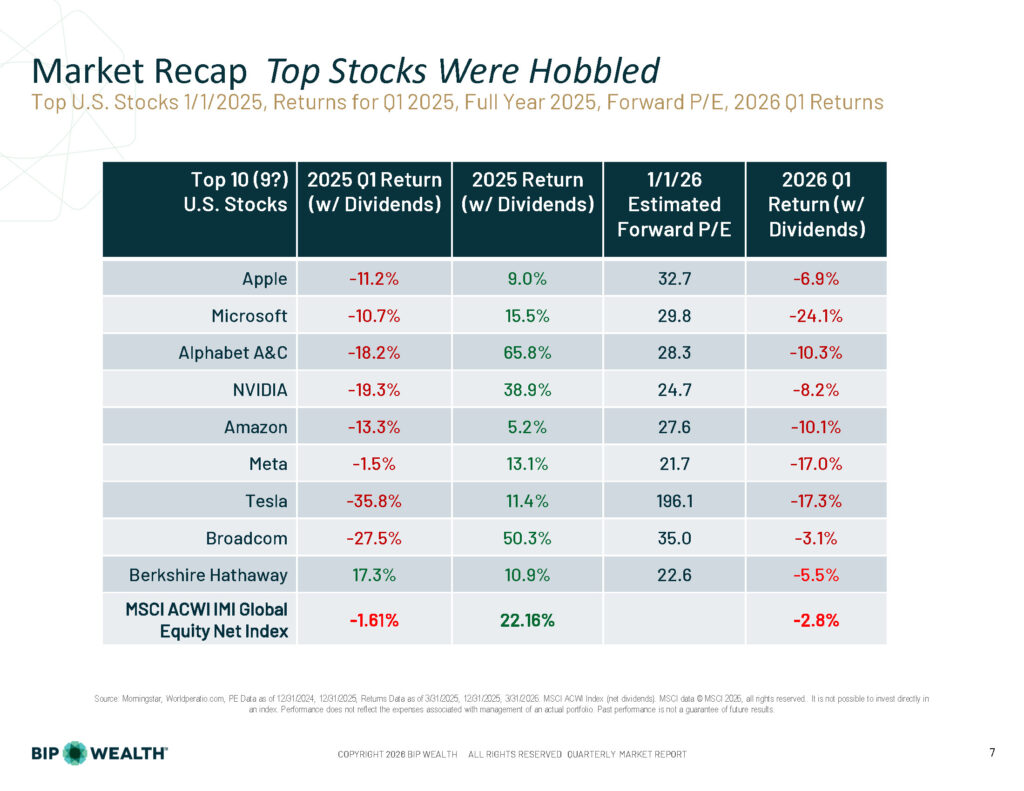
What happened in 2025 is turning out to be the template for what's happening in 2026. High valuations with these top 10 stocks, big sell-off in the first quarter, and then a rally to begin to bring most of these back.
Source: Morningstar, Worldperatio.com. PE Data as of 12/31/2025, Returns as of 3/31/2026. For illustrative purposes only. Past performance is not a guarantee of future results.
If you followed our Annual Market Report earlier this year, this story will feel familiar. The top 10 U.S. stocks—companies like Apple, Microsoft, NVIDIA, and Meta—now represent roughly 40% of the total U.S. market. They entered 2026 with elevated valuations, and in Q1 they paid for it: nearly every name on that list posted significant negative returns, some by double digits.
The good news? Just like in 2025, these stocks have largely started to recover as Q2 has unfolded. The pattern is holding: high valuations, a Q1 selloff, then a rebound. That doesn't mean Eric is comfortable with those valuations, it just means staying diversified and staying invested has, once again, been the right call.
For the broader market, the MSCI ACWI IMI Global Equity Net Index was down 2.75% in Q1. Fixed income was essentially flat. If you're diversified across asset classes and geographies, you likely weathered the quarter without much drama.
Source: Russell/MSCI. For illustrative purposes only. Past performance is not a guarantee of future results. Indices are not available for direct investment.
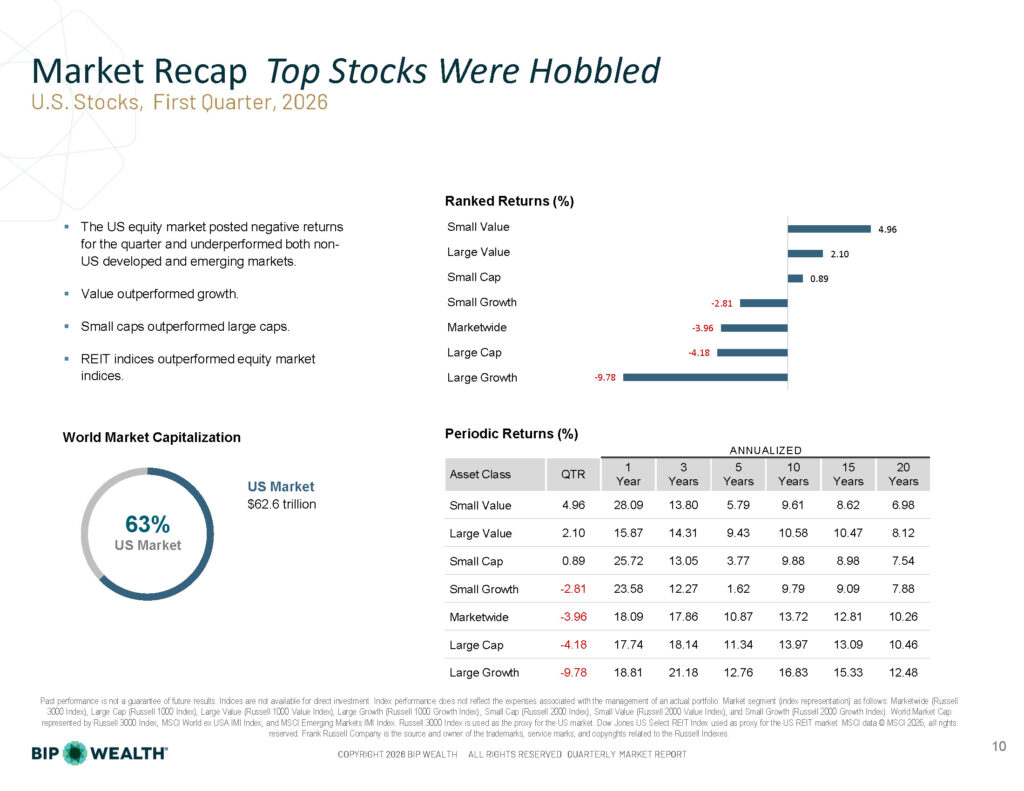
This quarter confirmed a trend we've been tracking for several quarters now: the U.S. has not been the best place to invest. That's not a permanent indictment—we still maintain a modest U.S. overweight, as most advisors do—but the data keeps pointing in the same direction.
Within the U.S., value outperformed growth and small caps outperformed large caps. These are results broadly consistent with what long-term historical data would predict. Small Value returned +4.96% for the quarter while Large Growth fell -9.78%. This is exactly what we'd expect when the high-flying, high-valuation names run out of momentum.
Overseas, the story was similar. International developed markets declined modestly in USD terms but still outperformed the U.S. Emerging markets, despite posting slightly negative Q1 returns, and have had a standout trailing year. As mentioned in a previous blog from Eric, Emerging markets have quietly continued to lead the recovery in Q2 so far.
Source: Federal Reserve. For illustrative purposes only.
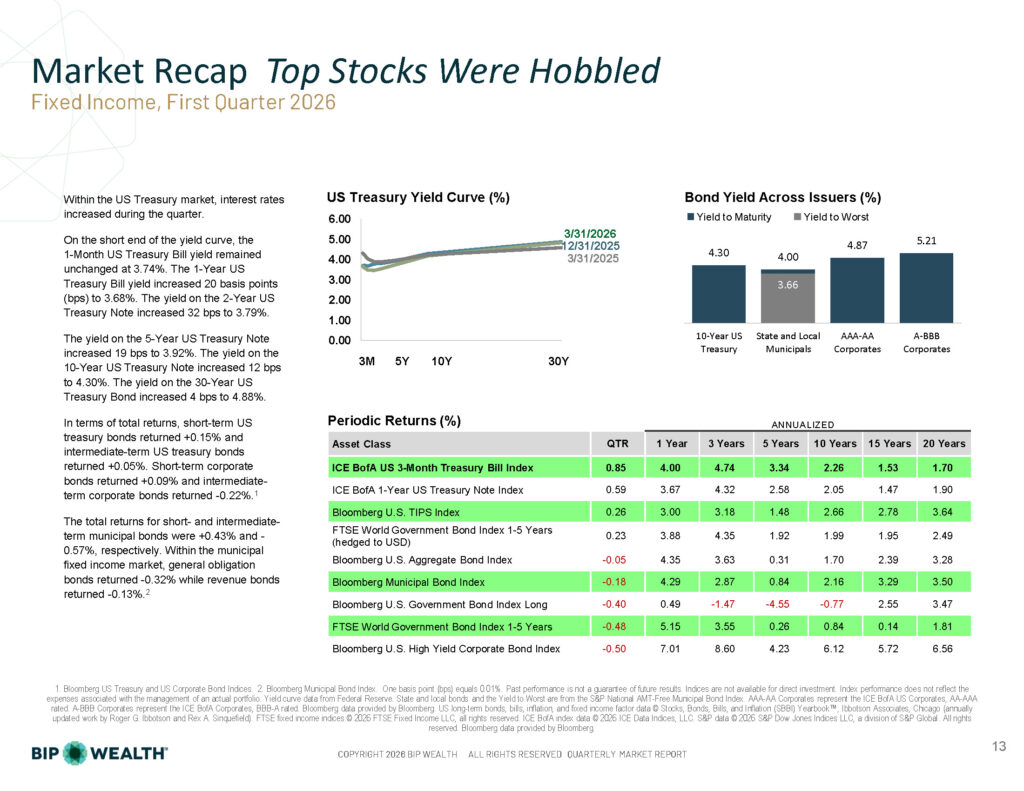
One thing Eric pointed out that doesn't always get attention: the yield curve is looking reasonably normal right now. Short-term rates are lower than long-term rates, which is exactly how it's supposed to work. When we see severe distortions on the short end of the curve, it usually signals the Fed is either too aggressive or too loose. Right now, the market seems to believe the Fed's posture is appropriate.
That said, rates did tick up across most maturities during the quarter: the 10-Year Treasury yield moved to 4.30%, and the 30-Year to 4.88%. For clients near or in retirement who rely on fixed income, the one-year return on the Bloomberg U.S. Aggregate of 4.35% is reasonable. But to be clear, over a 10- or 20-year horizon, the real risk is being too conservative. Equities have historically delivered meaningful premiums over fixed income over long periods, and that relationship held again over every multi-year period shown in our blended benchmark data.
This is the big question. Eric doesn’t know the answer yet, and he’s not convinced anyone else does either. But it's important to understand what we're watching and why it matters.
Stagflation occurs when economic growth slows at the same time inflation rises. It's a particularly painful combination because the normal policy tools work against each other—cutting rates to spur growth can make inflation worse; raising rates to fight inflation can suppress growth further. We saw it in the 1970s and early 1980s, and it was rough.
Here's what concerns Eric right now:
Economic growth may be softening. The Atlanta Fed's GDPNow model was forecasting just 1.24% real GDP growth for Q1 as of late April (though that number has since climbed back toward 3.5%, a reminder of how volatile real-time forecasts are). Reliable GDP data is always a year behind by the time it's been revised; we're navigating with incomplete maps.
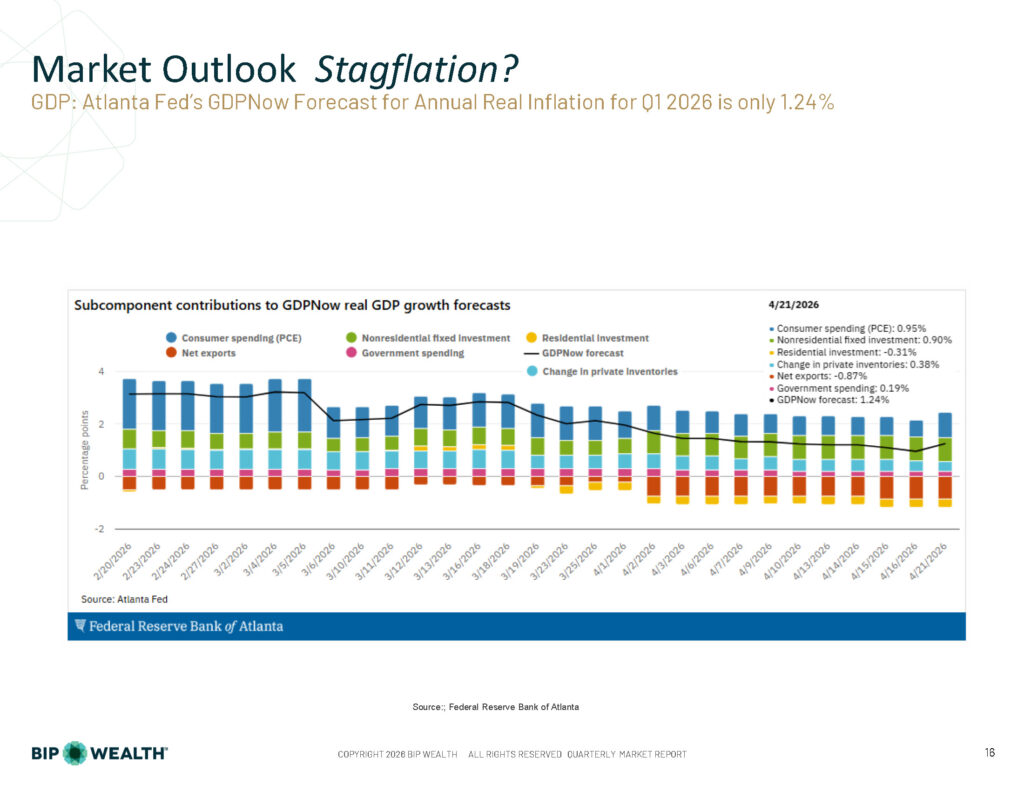
Source: Federal Reserve Bank of Atlanta. For illustrative purposes only.
Inflation may be picking up. CPI data has become less reliable than it used to be: survey response rates are down, and some government data collection has been underfunded. But the trajectory appears to be moving higher. If we look at the historical record going back to 1970, virtually every major inflation spike has been followed by a recession. The one exception in recent memory was post-COVID, and we were right at the time to say we didn't think a recession was coming. We were right then. Whether that holds again is less certain.
"If you start to see inflation spike in the near term, most of the time that means we're going to have a recession. So we're certainly watching out for it."
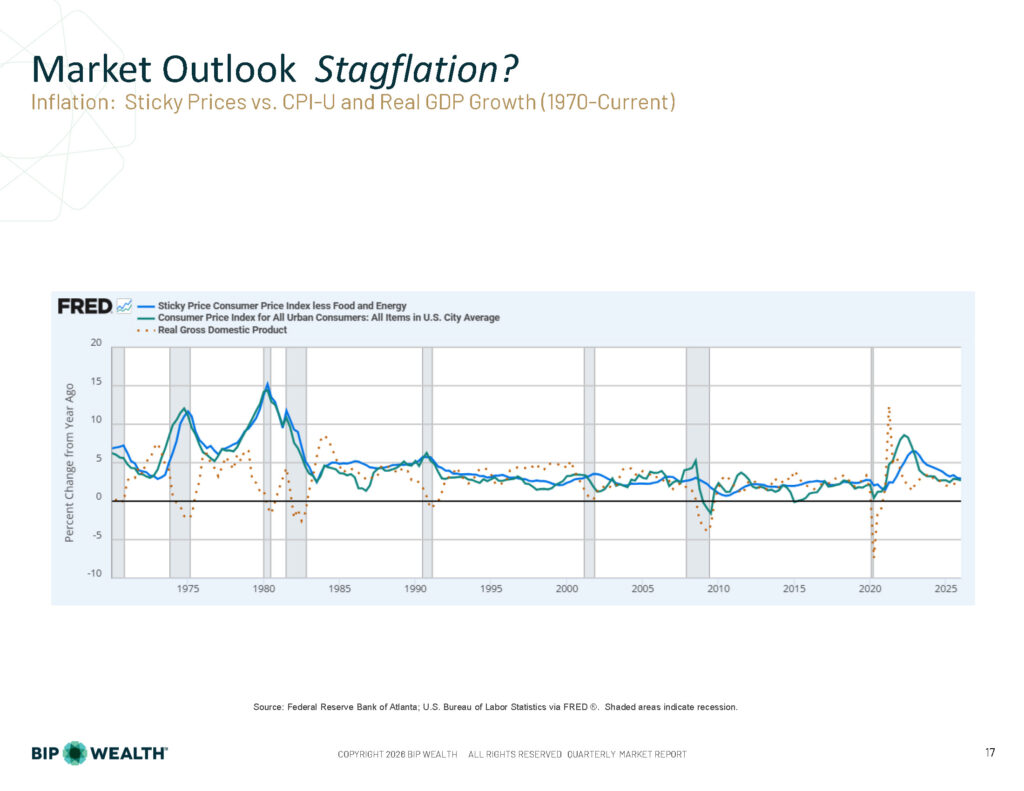
Source: Federal Reserve Bank of Atlanta; U.S. Bureau of Labor Statistics via FRED®. Shaded areas indicate recessions.
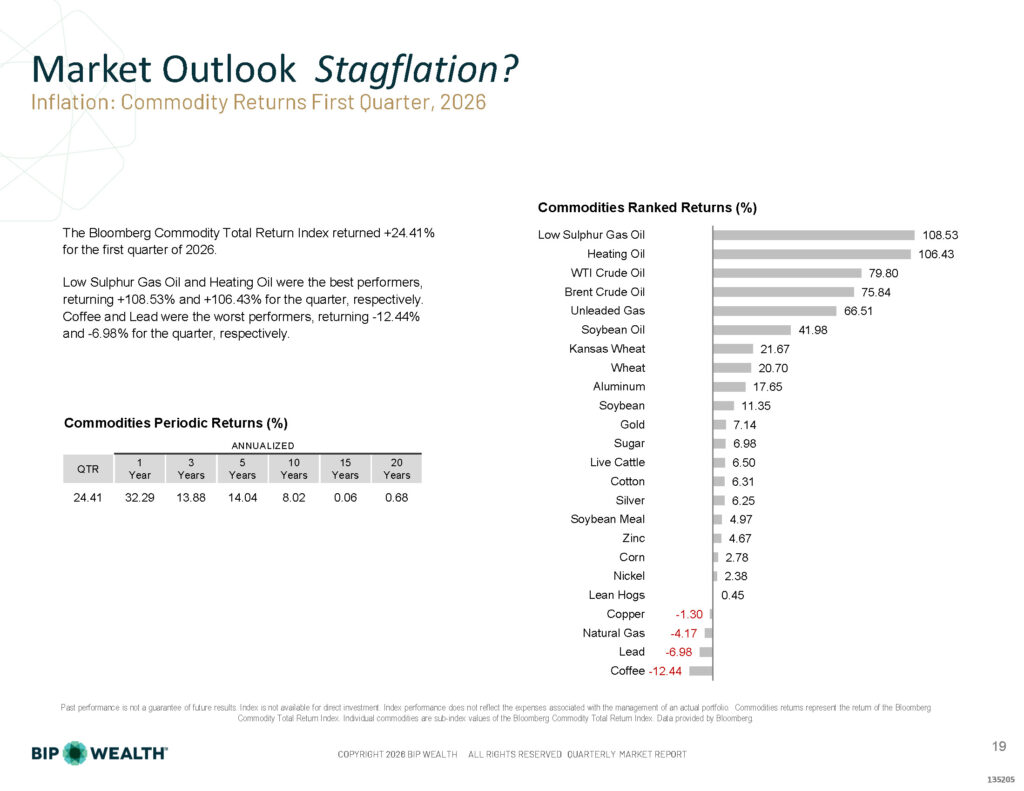
Source: Bloomberg Commodity Total Return Index. For illustrative purposes only. Past performance is not a guarantee of future results.
The Bloomberg Commodity Total Return Index returned +24.41% in Q1 2026. That number alone should get your attention. Energy led the way with Low Sulphur Gas Oil and Heating Oil each roughly doubled in the quarter. Crude oil was not far behind.
One nuance worth calling out: the spot price of oil and the futures price are not the same thing, and much of what gets reported in financial media reflects futures prices. At the beginning of April, the Europe Brent spot price hit around $127 per barrel—roughly $30 higher than futures at the time. Some refineries around the world were paying $150–175 per barrel in isolated transactions on the spot market. That difference matters; it’s what actually hits consumers and businesses in the short term.
Add to that the fact that the Strait of Hormuz disruptions continue to affect supply chains, and you have a recipe for continued inflationary pressure in the quarters ahead.
One of our four key themes for 2026 is "Shifting Global Trade Power," and Q1 gave us more evidence that this trend is accelerating.
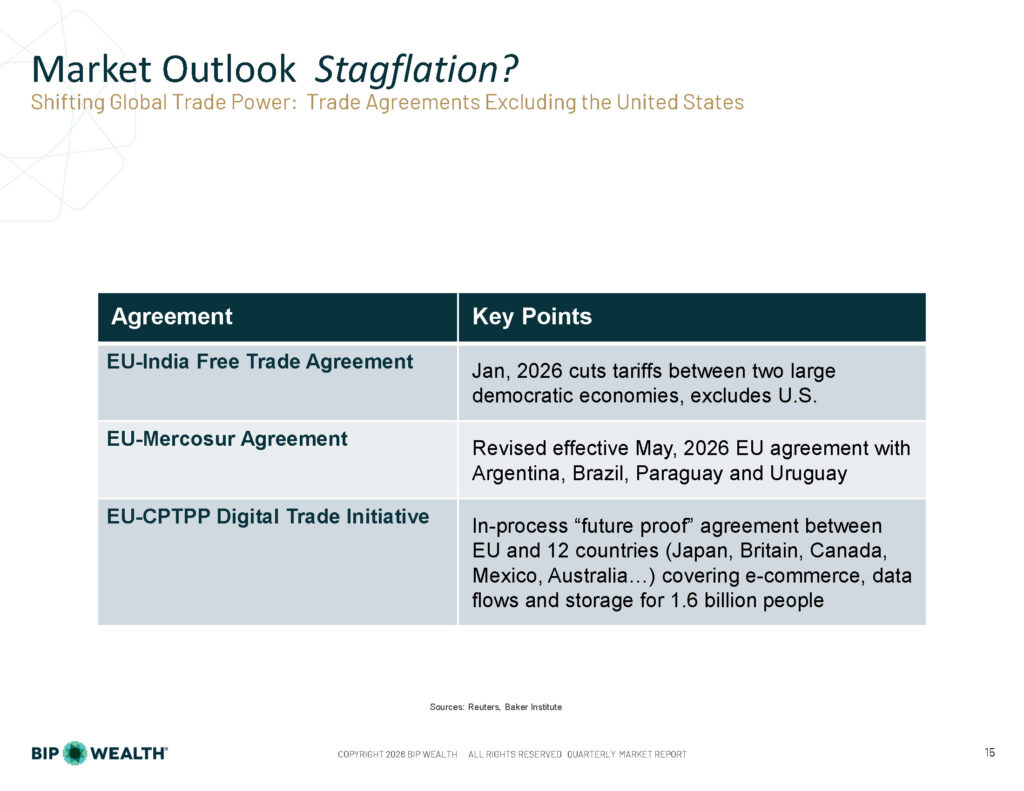
Sources: Reuters, Baker Institute.
Three significant trade agreements—the EU-India Free Trade Agreement, the revised EU-Mercosur Agreement, and the in-progress EU-CPTPP Digital Trade Initiative—are all designed to chart a course that doesn't depend on U.S. participation. I remember watching something similar happen after COVID, when global companies scrambled to reduce their reliance on Chinese supply chains. What we're seeing now is a version of that, but applied to U.S. economic policy uncertainty.
All parties are making moves to protect what they perceive is in their own best interests. And the net effect of that could be that the United States is just becoming more and more isolated.
“This isn't necessarily a catastrophe. But it does mean the environment is changing, and investors should expect the data to look different going forward: more volatility in the dollar, more pressure on trade-sensitive sectors, and potentially lower long-run U.S. growth relative to international markets.”
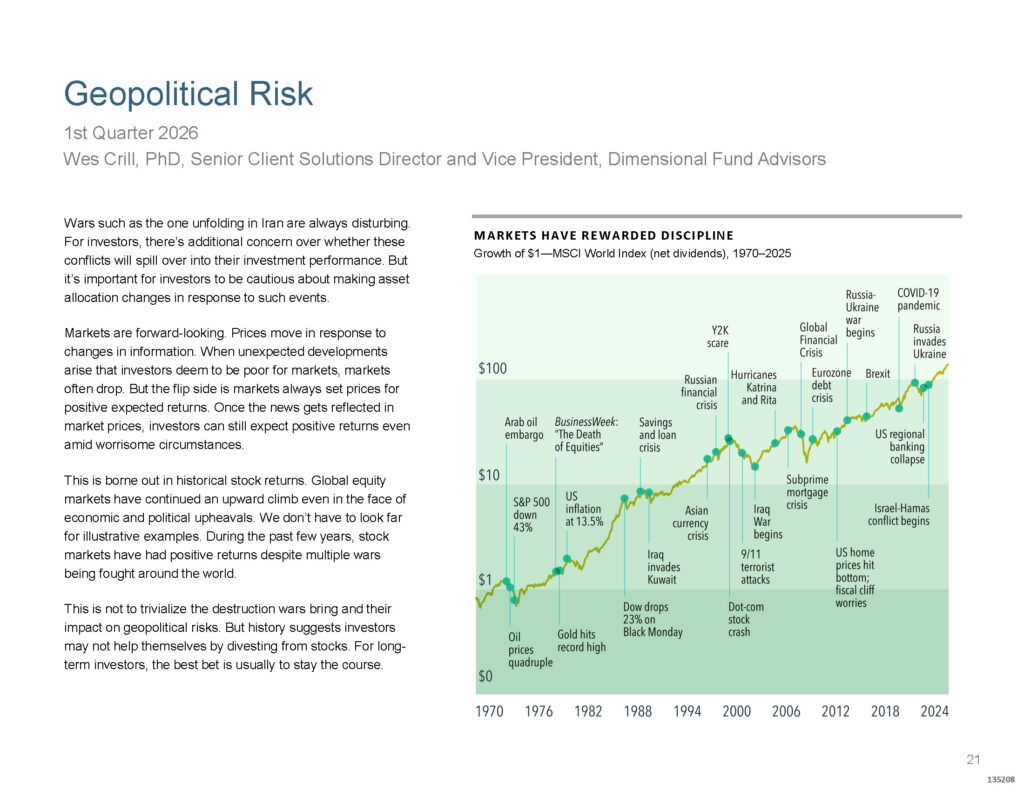
Source: Dimensional Fund Advisors. Past performance is not a guarantee of future results. Index is not available for direct investment.
Eric closed with something worth repeating: current events always feel unsettling when you're living through them. The Arab oil embargo. Black Monday. 9/11. The Global Financial Crisis. COVID. In every one of those moments, there were credible arguments for why this time was different, why capitalism was broken, why markets would never recover.
They were wrong. Every time.
"Sometimes it's like standing on the edge of a cliff, waiting for a gust of wind that might blow you over. That's kind of a normal thing. But democracy, capitalism, property rights, rule of law, and just the innovative spirit of millions of human beings will cause us to be rewarded for our faith in the stock market in the long run."
We may or may not see stagflation materialize in the quarters ahead. But the conditions worth watching are real, and the right response isn't to react to every headline. It's to stay diversified, keep your financial plan current, and make sure your allocation reflects your actual time horizon. If you have questions about how any of this applies to your situation, reach out to us to connect with a BIP Personal Wealth advisor.
This publication contains general investing information that is not suitable for everyone and is subject to change without notice. Past performance is no guarantee of future results and there is no guarantee that any views and opinions expressed will come to pass. Any reference to market or index performance is for informational and illustrative purposes only and does not reflect the deduction of fees and does not represent actual portfolios. The information contained herein should not be construed as personalized investment advice, tax advice, or financial planning advice, and should not be considered a solicitation to buy or sell any security. Investing in the stock market and the bond market involves gains and losses and may not be suitable for all investors.
BIP Wealth, LLC is a registered investment adviser. Registration does not imply a certain level of skill or training. Additional information about BIP Wealth is available on the SEC's website at www.adviserinfo.sec.gov.
Kevin Warsh is about to become the next chair of the Federal Reserve, and I want to be honest with you: I don't envy him one bit.
As chair, Warsh will lead the Federal Open Market Committee—12 voting members in total, made up of the seven Board of Governors, the president of the New York Fed (a permanent voter), and four regional Federal Reserve Bank presidents who rotate in on one-year terms. Together, they carry the weight of three congressional mandates: price stability, full employment, and keeping long-term interest rates at a moderate level (the oft forgotten third mandate from Congress since 1977).
That third one matters enormously right now. Compared to what he's walking into, some of Kevin’s predecessors had it easy. Managing this economy in 2026 is a little like trying to nail Jello to a wall. Let's all wish him the best of luck, for our sake.
Most of the time, the Fed keeps its eyes on consumer demand. When people spend too much, prices rise, and the Fed raises rates to cool things off. Simple enough in theory.
But what we're dealing with now is a supply shock, and those are much harder to manage with interest rate policy. We saw this play out just a few years ago when pandemic-era supply chain breakdowns sent inflation spiraling. China's zero-tolerance COVID policies contributed to a massive, policy-driven disruption that helped push the CPI-U (the Consumer Price Index for Urban Consumers) to a 9.1% annual rate in June 2022. At that point, the Fed had stayed committed to low short-term rates for far too long, and it became one of the bigger policy failures in recent memory.
Now, in early 2026, commodity prices are rising again across the board, with oil and refined products leading the way. The Producer Price Index climbed 1.4% in April, bringing its trailing twelve-month reading to 6.0% through April 2026. For context, the full-year 2022 PPI came in at 6.2%. We're almost there. So the question a lot of people are asking, and that I'm taking seriously, is if we’re going to see retail inflation measures like the CPI-U jump to 9% again?

Source: This chart from BIP Wealth's January 2023 Annual Market Report shows the Bloomberg U.S. Aggregate Bond Index's historic decline in 2022.
When the last inflation surge hit, BIP Wealth was proactive in lowering the risks of rising rates in client portfolios. We pivoted much of our fixed income exposure to mimic the returns of the 3-month Treasury Bill Index rather than holding longer-duration bonds. The Bloomberg U.S. Aggregate Bond Index fell 13.01% in 2022, its worst annual performance ever. Our clients were protected from the brunt of that.
We are running the same play today. We've already reduced interest rate exposure in client portfolios, and we're also taking profits from the equity run-up. Maybe the AI-driven boom can continue despite these macro headwinds, but we're not counting on it.
There's another piece of this story worth mentioning: the Fed's balance sheet.

Source: Federal Reserve Bank of St. Louis (FRED). The chart shows the balance sheet decline slowing in 2025 and now beginning to reverse upward.
In recent months, the Fed halted its so-called "quantitative tightening"—the gradual reduction of the massive bond portfolio it built up post-2008 and again post-pandemic. Not only did it stop selling, it has started buying Treasury bonds in the open market again. The effect of that is to suppress long-term interest rates, since the Fed is willing to accept whatever rate is offered. It also helps the U.S. Treasury to finance the annual budget deficit more cheaply at lower rates.
But here's the catch: expanding the balance sheet means expanding the money supply. And more money chasing the same amount of goods leads to one thing: inflation! This is precisely why Warsh has stated publicly, for years, that he wants to shrink the Fed's balance sheet. Whether he'll actually be able to do that is the big question.
So here's where Kevin Warsh finds himself, and why this matters to you.
If he lowers short-term interest rates—which the White House favors, and which many believe he was selected partly to deliver—he risks pouring fuel on an inflationary fire that's already burning hotter than most people realize. Warsh declared his independence during his Congressional confirmation hearings, but if he follows the path Powell took in 2021, we'll likely see prices accelerate at the worst possible time.
If he shrinks the Fed's balance sheet, as he has long advocated, be prepared for long-term interest rates to move meaningfully higher. The 30-year Treasury yield has already been flirting with 5% for weeks. A move toward 6% or higher would push mortgage rates up sharply, potentially crater the housing market, and significantly increase the cost of financing the national debt.
That debt is now nearly $40 trillion, larger than our entire annual GDP. Every percentage point increase in financing costs forces even more Treasury issuance to cover the interest, which compounds the problem further.
There's no clean path here. He may have to choose between inflation and a credit crunch. That's the Jello-on-the-wall problem.
Kevin Warsh is walking into one of the more genuinely difficult jobs in recent Fed history. Supply shocks don't respond neatly to rate policy. The balance sheet is expanding again. Commodity prices are climbing. And the political pressure to keep rates low is real.
At BIP Wealth, we're not waiting to see how it plays out. We've already adjusted. Whether Warsh turns out to be the person who can nail Jello to a wall, we'll find out soon enough.
If you want to talk through how your portfolio is positioned heading into this period of uncertainty, reach out to us to connect with a BIP Personal Wealth advisor.
This blog is provided for informational and educational purposes only and does not constitute investment advice or a recommendation to buy or sell any security. Investing involves risk, including the potential loss of principal. Past performance is not a guarantee of future results. Fixed income investments are subject to interest rate risk; bond values generally decline when interest rates rise. References to the Bloomberg U.S. Aggregate Bond Index and 3-Month Treasury Bill Index are for illustrative purposes only; indices are unmanaged and not available for direct investment.
The Consumer Price Index (CPI-U) and Producer Price Index (PPI) are published by the U.S. Bureau of Labor Statistics. Federal Reserve balance sheet data sourced from the Federal Reserve Bank of St. Louis (FRED).
Statements regarding BIP Wealth's past portfolio positioning are historical in nature and are not indicative of future results or actions. BIP Wealth is a registered investment advisor with the U.S. Securities and Exchange Commission. Registration does not imply a certain level of skill or training.
Emerging markets and small caps are quietly stealing the show in 2026.
If someone asked you how the stock market has been doing so far in 2026, you'd probably mention that tech stocks had a rough first quarter—and that they've been bouncing back. That's the story most people have been following. But here's a number that might stop you in your tracks: emerging market stocks have outperformed the S&P 500 by roughly 9 percentage points year-to-date through April in 2026.
That's not a rounding error. That's a trend worth paying attention to.
The real story of 2026—at least through the first few months—is an Emerging Markets and U.S. Small Cap rally. The MSCI Emerging Markets Index is up over 14% YTD, while the Russell 2500 (which captures all the U.S. stocks not in the S&P 500) is up over 13%. The S&P 500, by comparison, is up just under 6%.
The one-year numbers tell a similar story. Emerging markets are up nearly 48% over the past twelve months. The Russell 2500 is up 40%. The S&P 500? A solid 31%—but clearly not the top performer.
| Index | 1 Mo | 3 Mo | YTD* | 1-Year | |
|---|---|---|---|---|---|
| 100% Fixed Income | Bloomberg U.S. Aggregate (Total) | 0.23 | 0.09 | 0.28 | 4.24 |
| 100% Global Equity | MSCI All Cap World Index IMI (Net) | 10.12 | 3.70 | 7.09 | 31.62 |
| Cash | S&P U.S. Treasury Bill 0-3 Mo (Total) | 0.30 | 0.89 | 1.19 | 4.08 |
| Municipal Bonds | Bloomberg Municipal 1-15 Bond (Total) | 0.80 | -0.53 | 0.53 | 5.98 |
| Domestic Large Cap Equity | S&P 500 (Total) | 10.49 | 4.19 | 5.70 | 31.05 |
| Domestic Mid/Small Cap Equity | Russell 2500 (Total) | 11.15 | 8.03 | 13.41 | 40.10 |
| International Developed Market Equity | MSCI EAFE (Gross) | 7.56 | 1.08 | 6.36 | 25.22 |
| International Emerging Market Equity | MSCI Emerging Markets (Gross) | 14.73 | 5.28 | 14.61 | 47.51 |
*As of 4.30.2026. For illustrative purposes only. Past performance is not indicative of future results. The indices referenced are unmanaged and cannot be invested in directly. International investing involves additional risks including currency fluctuations, political instability, and different accounting standards. Emerging markets involve heightened risks related to the same factors as well as increased volatility and lower trading volume. Small cap stocks may be subject to higher degrees of risk than large cap stocks. BIP Wealth, LLC is a registered investment adviser. Registration does not imply a certain level of skill or training. More information on these specific indices is included below.
Those of us who've been doing this job for a while will remember when emerging markets and small caps were considered the most exciting corners of the stock market. That narrative faded during the long dominance of U.S. large cap growth stocks—particularly the mega-cap tech names that drove most of the S&P 500's returns over the past decade.
But here's the thing: valuation matters over time. Emerging market and small cap stocks are still significantly cheaper than U.S. large caps when measured by price-to-earnings ratios (P/E). That valuation gap is one reason there's a rational case to be made that this trend has room to continue.
This doesn't mean the S&P 500 is broken or that U.S. large caps are going away. It means that a well-diversified portfolio—one that includes exposure to international and smaller-company stocks—may look a lot smarter right now than it did a few years ago when U.S. large caps were winning everything.
If your investments carry heavy U.S. large cap concentration—which, for many investors, is the default—this is a good moment to revisit your global diversification strategy. Not because the S&P 500 is doing poorly, but because other parts of the market are doing better, and for reasons that could persist.
At BIP Wealth, we build portfolios with global diversification in mind precisely because we don't know which corner of the market will lead in any given year. This kind of year is a strong case for portfolio diversification beyond U.S. large caps and a good reminder of why that approach matters.
International diversification, small cap exposure, emerging market allocations—these aren't "alternative" in the sense of exotic. They're part of a thoughtful, long-term portfolio construction strategy.
The biggest market story of 2026 isn't the tech rebound. Emerging markets are outperforming the S&P 500 by nearly 9 percentage points year-to-date, and U.S. small cap stocks aren't far behind. Cheaper price-to-earnings valuations and improving fundamentals suggest this may not just be a blip; and for investors with a well-diversified global portfolio, that's meaningful.
If you're curious how your current allocation stacks up, reach out to us to connect with a BIP Personal Wealth advisor.
The Bloomberg U.S. Aggregate Bond Index is a broad-based benchmark selected as the best available proxy for a high quality, diversified fixed income portfolio suitable for a U.S. investor. It is comprised of the Bloomberg U.S. Government/Credit Bond Index, the Mortgage-Backed Securities Indices, and the AssetBacked Securities Index. It is an unmanaged market value-weighted performance benchmark for investment-grade fixed-rate debt issues, with maturities of at least one year, and an outstanding par value of at least $100 million. The "Total Return" version of the index is reported here, which means that dividends are included and reinvested.
The MSCI ACWI IMI Index is a free float-adjusted market capitalization weighted global index selected as the best available proxy for a diversified stock portfolio consistent with modern portfolio theory. Approximately 60% of the index is comprised of the U.S. stock market and 40% is comprised of international stock markets, including both developed and emerging countries. The "Net Total Return" version of the index is reported here, which means the index reinvests dividends after the deduction of withholding taxes, using a tax rate applicable to non‐resident institutional investors who do not benefit from double taxation treaties.
The S&P U.S. Treasury Bill 0-3-Month Index is designed to measure the performance of U.S. Treasury bills maturing in 0 to 3 months.
The Bloomberg Municipal 1-15 Year Index is a broad-based benchmark that covers the U.S. dollar denominated long-term tax exempt bond market. The index has four main sectors: state and local general obligation bonds, insured bonds, and pre- refunded bonds. The "Total Return" version of the index is reported herein, which means that interest is included and reinvested.
The S&P 500 Index is a market capitalization weighted index that consists of 500 widely traded stocks chosen for market size, liquidity, and industry group representation. The "Total Return" version of the index is reported herein, which means that dividends are included and reinvested
The Russell 2500 Index is a free float-adjusted market capitalization weighted index intended to represent the smallest 2500 of the top 3000 U.S. companies. The "Total Return" version of the index is reported herein, which means that dividends are included and reinvested.
The MSCI EAFE Index is a free float-adjusted market capitalization weighted index that is designed to measure the equity market performance of international developed markets, excluding the U.S. and Canada. EAFE refers to Europe, Australasia, and the Far East and includes 21 individual countries that collectively represent many of the major markets of the world. The "Gross Return" version of the index is reported herein, which means that dividends are included and reinvested and there is no withholding tax applied to reduce returns.The MSCI Emerging Markets Index is a free float-adjusted market capitalization weighted index that is designed to measure the equity market performance of international emerging markets. It includes 21 individual countries that collectively represent many of the developing markets of the world. The "Gross Return" version of the index is reported herein, which means that dividends are included and reinvested and there is no withholding tax applied to reduce returns.
Copyright 2026 BIP Wealth. All rights reserved.
When most people hear "private credit," their eyes glaze over somewhere between "senior secured" and "subordinated debt." That's understandable. The terminology sounds like it was designed to keep outsiders out. But the underlying concept is surprisingly intuitive once you see it laid out properly.
At its core, every private credit conversation comes down to one question: where does your money sit if something goes wrong?
That's what the capital stack tells you.
The capital stack is the hierarchy of claims on a company's assets and cash flows. It determines who gets paid first, and who absorbs losses first, when a borrower runs into trouble.
Think of it as a line at the bank. The people at the front of the line, senior secured lenders, get paid first, no matter what. The people at the back of the line, common equity holders, only get paid if there's anything left after everyone ahead of them has been made whole. The further back you stand, the more you might earn for your patience, but the greater the chance you walk away empty-handed.
The layers near the top of the capital stack, working capital and senior secured debt, get repaid before anyone else. They're typically backed by tangible assets: cash, receivables, equipment, real property. The layers near the bottom, preferred and common equity, absorb losses first and get repaid last.
Every layer exists for a reason, and every layer earns a different return that reflects the level of risk the investor is accepting. The relationship between position and risk isn't complicated, but it may be one of the most important concepts in private credit investing.
The interactive graphic below maps out the full capital stack alongside a company's enterprise value: the assets that back these obligations. Take a moment to hover over each layer to see what it means and how it relates to risk and return.
Headlines tend to focus on the extremes. Equity investors making a fortune or losing everything generates clicks. But the most interesting part of the capital stack for many investors is the middle, specifically, senior secured direct lending.
Here's why. Senior secured loans sit high enough in the stack that the borrower's tangible assets serve as a meaningful safety net. If a company can't make its payments, senior secured lenders have priority claim on those assets ahead of subordinated lenders, ahead of equity holders, ahead of everyone except the most short-term obligations at the very top.
At the same time, these loans may offer yields that meaningfully exceed what most traditional fixed income instruments have historically provided. That combination, repayment priority plus competitive income potential is what has drawn significant institutional capital to this space.
The tradeoff? Liquidity. Unlike a publicly traded stock you can sell on an exchange in seconds, private credit investments are typically held in evergreen fund structures with specific redemption windows and potential limitations on withdrawals. That reduced liquidity is actually part of the design which may help prevent the kind of forced selling that can destabilize public market strategies during periods of stress. However, investors should understand that their ability to access capital may be limited during certain periods.
This is the part where the capital stack visual becomes genuinely useful as an educational tool. When someone says they "invest in private credit," that phrase alone doesn't tell you much. A subordinated debt fund and a senior secured direct lending fund are both technically private credit, but they occupy very different positions in the repayment line.
Subordinated debt may earn a higher coupon because the investor is accepting more risk—they're further back in line if the borrower encounters difficulties. Convertible debt adds another dimension: it starts as a loan but can transform into ownership under certain conditions. Mezzanine financing sits in between, bridging the gap between debt and equity with characteristics of both.
Each of these strategies has a place in portfolio construction. But knowing which layer you're investing in and understanding why it may pay what it pays can be the difference between a thoughtful allocation and a decision based on a label.
BIP Wealth's private credit strategies concentrate on diversified, senior secured, direct lending backed by private equity sponsors. In practical terms, that means lending to established, middle-market companies where a large investment firm has performed due diligence, negotiated protective covenants, and has its own capital at stake alongside investors.
The objective isn't to chase the highest available yield on the capital stack. It's to target the layer where the historical risk-adjusted characteristics have been favorable, and where the structural protections provide a foundation for confidence across varying economic environments.
BIP Wealth complements this core approach with exposure to asset-based lending and, selectively, other strategies when they align with a client's overall financial plan and risk tolerance.
The goal is never to maximize a single variable. It's to construct a portfolio designed to seek consistent, reliable income without taking on more risk than the investor's situation warrants.
Private credit strategies involve risks including the potential loss of principal, limited liquidity, and sensitivity to interest rate changes. Past performance of any strategy is not indicative of future results.
The capital stack isn't just an academic framework, it may be the single most important factor in understanding what you actually own when you invest in private credit. Before evaluating any fund, any headline, or any investment opportunity, start with one question: where in the line am I standing?
If you understand that, everything else falls into place.
If you'd like to learn more about how private credit may fit within your overall portfolio, reach out to us to connect with a BIP Personal Wealth advisor.
This post is provided for informational purposes only and should not be construed as investment advice or a recommendation to buy or sell any securities. Ideas and opinions expressed represent the views of BIP Wealth and are subject to change without notice. Private credit investments involve risks, including the potential loss of principal. Privately traded offerings may only be available to investors who meet certain qualification statuses. There can be no assurance that actual outcomes will match any expected returns. Past performance is not a guarantee of future results. All investing involves risk, including the possible loss of principal. BIP Wealth is a registered investment advisor. Registration with the SEC does not imply a certain level of skill or training.
As we shared during our 2026 Annual Market Report presentations, we expected the Federal Reserve to hold steady on interest rates for the foreseeable future. That view was firmly reinforced following the Fed's meeting on Wednesday, March 18th, where futures market pricing left little doubt: the current overnight rate is likely here to stay.
The futures market—where investors express their convictions with dollars rather than words—currently points to the Fed maintaining the existing Federal Funds Rate all the way through the April 28th, 2027 meeting. This rate directly influences money market yields and margin borrowing costs, making it a meaningful benchmark for investors across the board.
That said, the picture isn't entirely static. While a prolonged pause appears most likely, there remains a meaningful and asymmetrical probability that rates could move lower before the end of 2026. Specifically, futures pricing reflects a measurable chance of cuts of 25 or even 50 basis points by year end, while the probability of a rate increase is, by contrast, nearly zero. The Fed's "dot plot," which captures where individual members see rates heading, doesn't yet reflect a clear consensus, but it does leave the door open to a cut later this year.
One of the key variables to watch will be energy prices. History shows a strong correlation between oil price movements and future inflation, and with ongoing volatility in the region as the situation in Iran continues to develop, energy markets will remain an important signal. We believe futures pricing is among the best real-time tools available for tracking how these dynamics are evolving and we will continue monitoring them closely on your behalf.
As always, we'll keep you informed as the landscape shifts. For those who want to explore the data directly, the CME FedWatch Tool offers an up-to-date view of rate expectations as priced by the market.
This post is provided for informational purposes only. Specific investments may not be suitable for all investors and no offer or recommendation of any investment or investing strategy is intended or implied by your choosing to read this post. This material is not intended to be relied upon as a forecast or investment advice regarding a particular investment or the markets in general, nor is it intended to predict or depict the performance of any investment. The third-party information in this post is from sources we believe to be reliable, but BIP Wealth cannot guarantee its accuracy.
